Flowers Foods Lowers Outlook (Again) as Bread Category Competition Rises

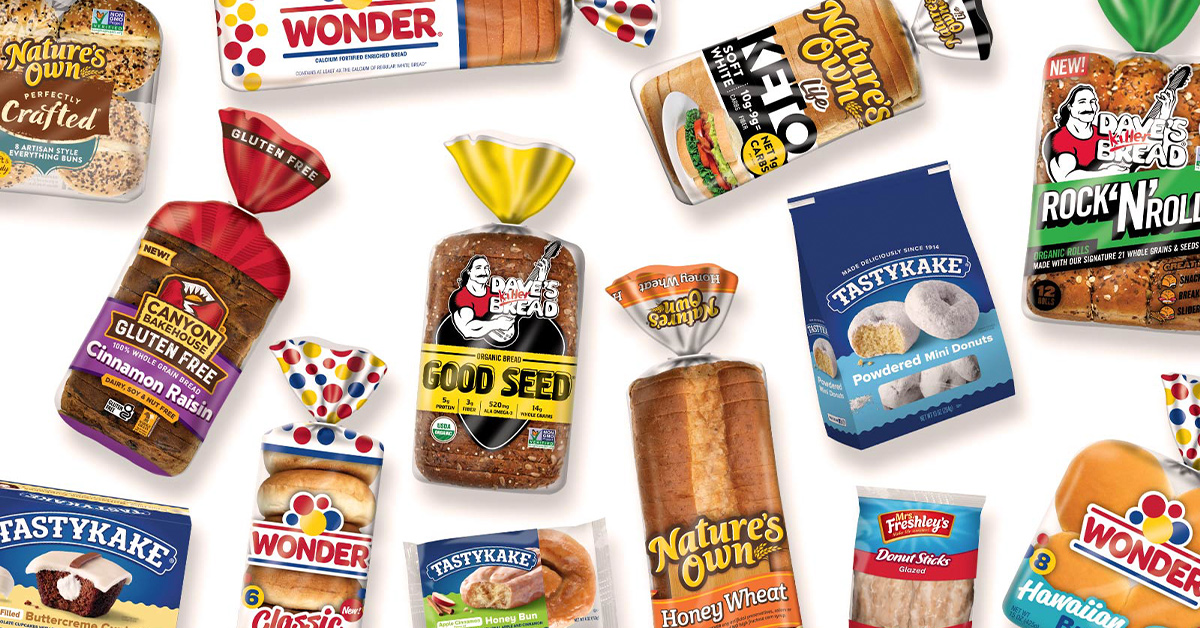
Flowers Foods has again downgraded its full-year guidance after posting mixed second quarter results, citing headwinds such as macroeconomic uncertainty and more intense competition in the bread category.
In the quarter ended July 12, net sales notched up 1.5% year-over-year to $1.24 billion, as the company’s Simple Mills acquisition more than offset pricing/mix and volume declines. Net income decreased 12.8% to $58.4 million, representing 4.7% of sales.
Shifting consumer trends have had an outsized impact on bread, according to CEO Ryals McMullian, with sales underperforming the general food category. Traditional loaf products, an area that the Dave’s Killer Bread (DKB) and Nature’s Own maker is “especially exposed to,” suffered particular pressure, with volumes sliding 6%. The introduction of new, lower-priced bread products hampered the company’s results.
In response, Flowers Foods is adapting its portfolio to align with current consumer trends such as better-for-you and value-oriented items that “targeted the strongest pockets of growth in the [bread] category.” The company’s promotional activity, which increased slightly over the year-ago period, remains focused on areas of strength, including DKB’s differentiated products, to drive trial and repeat purchases of new items.
“By addressing the factors within our control, we aim to maximize our near-term results while supporting more-consistent long-term growth. These initiatives are gaining momentum, underscoring what we believe to be the strength of our brands and the effectiveness of our strategy,” said McMullian in prepared remarks.
He claims consumers are willing to pay a premium for value-added attributes, as evidenced by the strong performances of Nature’s Own’s new Keto product line and DKB’s protein bars and snack bites.
To recapture consumers’ wallets, the company will continue expanding its product lines beyond bread in areas with significant market share potential, such as snacking. During its second quarter, Flowers Foods’ sweet baked goods business benefited from the spring launch of Wonder cakes, which reportedly outperformed the category and gained 70 basis points of unit share.
In the third quarter, the company is slated to roll out “a strong lineup of on-trend, innovative products” with an emphasis on better-for-you, value-oriented items, though management did not provide specifics.
It will also focus on the continued integration of Simple Mills, whose strong performance highlights its alignment with consumer trends. In the second quarter, the brand grew faster than any other natural cracker brand and maintained its leading market share in cookies.
Based on its lower-than-expected quarterly revenues, Flowers Foods has again downgraded its full-year guidance. The company now expects net sales between $5.23 billion and $5.3 billion (previously $5.3 billion to $5.4 billion) and adjusted EBITDA in the range of $512 million to $538 million (previously $534 million to $562 million).
“Macroeconomic uncertainty and shifting consumer demand have continued to pressure the bread category, but our portfolio strategy has shown promise in offsetting those headwinds,” said McMullian in a prepared statement. “We are proactively investing in innovation and M&A to transform our portfolio and align it with consumer demand for better-for-you and value-oriented products.”
Explore the Nombase CPG Database
Head to Nombase to learn more about the tagged companies and their offerings.